Guides · 2026–27 tax year
Published
How to Calculate Excess Reportable Income (ERI)
Your accumulating ETF didn't pay you anything, but HMRC says you've had income from it. Which date decides whether you're taxed, which year's tax return does it go on, and where do you find the figure?
The short answer
- To calculate excess reportable income, multiply the fund report's per-share figure by your shares when the reporting period ends, then convert it to pounds.
- Excess reportable income counts as received on the fund distribution date, 6 months after the reporting period ends. That date sets the tax year.
- Excess reportable income only comes from offshore funds with HMRC reporting fund status. Company shares, UK investment trusts and UK-based funds don't have it.
- Excess reportable income is added to what your fund shares cost you for Capital Gains Tax, so your gain is lower when you sell.
The two dates that matter
Excess reportable income (ERI) is income a fund has earned but not paid out to you. HMRC taxes you on it anyway, as if the fund had paid it. HMRC's own name for it is "excess reported income". This guide covers funds held in an ordinary account, outside an ISA or pension.
Two dates decide how it's taxed, and they're 6 months apart:
- The last day of the fund's reporting period decides whether you're taxed. If you hold shares in the fund at the end of that day, you get that period's ERI on every share you hold.
- The fund distribution date, 6 months after the end of the reporting period, is when the ERI counts as received for Income Tax. The tax year that date falls in is the year you report it.
The reporting period is the fund's own accounting year, not the tax year. Funds choose their own year end, so it isn't always 31 December. The fund's report gives both dates.
The date that decides whether you're taxed
It doesn't matter when you bought the shares, only whether you held them at the end of the reporting period. If you bought a week before it ended, you're taxed on the whole period's ERI for those shares. If you first bought during the period, equalisation may reduce the amount (see below).
If you sold before the period ended, you don't get that period's ERI. If you sold after the period ended but before the fund distribution date, you still do, because you held the shares at the end of the period.
The 30-day rule applies to ERI too. Say you sell just before the period ends and buy back within 30 days, in the next period. For ERI, HMRC treats you as still holding those shares at the end of the earlier period, so you're taxed on its ERI.
Which tax year it counts in
The ERI goes on the tax return for the tax year containing the fund distribution date, not the tax year the reporting period ends in. The tax year runs from 6 April to 5 April, and the online return and the tax are due by 31 January after it ends. For 2025–26, that's 31 January 2027.
A fund whose reporting period ends on 30 June
- You hold shares at the end of
- 30 June 2025
- Fund distribution date, 6 months later
- 31 December 2025
- Tax year it counts in
- 2025–26
A fund whose reporting period ends on 31 December
- You hold shares at the end of
- 31 December 2025
- Fund distribution date, 6 months later
- 30 June 2026
- Tax year it counts in
- 2026–27
Both reporting periods end in 2025, but the ERI counts in different tax years. So if you hold several funds, check each fund's dates rather than assuming they match.
Which investments have ERI
ERI only comes from offshore funds that have reporting fund status. That means the fund has applied to HMRC, been approved, and reports its income to UK investors for each reporting period.
A fund here means what the law calls a mutual fund. You and other investors pool your money, and a manager runs it without you making the day-to-day decisions. You can cash in at a price based on the value of the fund's investments or an index. ETFs, unit trusts and open-ended investment companies all work this way.
An offshore fund is one based outside the UK, such as a company resident in Ireland or Luxembourg. What counts is where the fund itself is based. An ETF can trade on the London Stock Exchange and still be an offshore fund.
These don't have ERI:
- Shares in companies, UK or foreign. They aren't mutual funds, because their price isn't based on the value of a pool of investments or an index.
- UK investment trusts and UK-based funds. They're resident in the UK, so they aren't offshore funds.
- Offshore funds without reporting fund status. These have no ERI, but when you sell, your gain is taxed as income at Income Tax rates, not as a capital gain.
An accumulating fund reinvests its income and a distributing fund pays it out, but ERI doesn't only come from accumulating funds. A distributing fund has ERI too if it pays out less than its reported income. If it pays out all of it, its ERI is zero, and the payouts are taxed as income when they're paid instead.
How to check your fund has reporting status
HMRC publishes a list of approved reporting funds and updates it every month. It's a large spreadsheet with one row per share class. A share class is one version of a fund, such as its accumulating or distributing version.
Find your fund's ISIN first. That's the code for the exact share class you hold, and it's usually shown in your broker's app and on the fund's factsheet. Your broker may show a ticker instead, the short code a share class trades under, such as VWRP. HMRC's list doesn't include tickers, so you need the ISIN. Then search the spreadsheet for it. The row shows the date the share class became a reporting fund, and the date it stopped, if it has.
Here's how five share classes appear on HMRC's list of 4 September 2026. I picked them to show how tickers, ISINs and share classes line up, not as suggestions to buy, sell or hold any of them. Being on the list is a tax status, not a sign that a fund is a good investment.
- VWRP: Vanguard FTSE All-World UCITS ETF (USD) Accumulating, ISIN IE00BK5BQT80, a reporting fund since 23 July 2019.
- VWRL: Vanguard FTSE All-World UCITS ETF (USD) Distributing, ISIN IE00B3RBWM25, a reporting fund since 24 May 2012.
- VALL: Vanguard FTSE Global All-Cap UCITS ETF USD Acc, ISIN IE000VAHT5T0, a reporting fund since 18 August 2026.
- HMWO: HSBC MSCI World ETF USD Distributing Share Class, ISIN IE00B4X9L533, a reporting fund since 8 December 2010.
- FTWG: Invesco FTSE All-World UCITS ETF Dist, ISIN IE0000QLH0G6, a reporting fund since 26 June 2023.
A share class that has stopped being a reporting fund has a date in the "Ceased to be an RF on" column. Status can change, so check the current list, not this one. VWRP and VWRL are two share classes of the same fund, with separate ISINs and rows. FTWG is the distributing class of its fund, and the accumulating class has a different ISIN.
Reporting status belongs to each share class, not the whole fund, so check the one you own. The fund's annual report to investors also says whether it's still a reporting fund.
To get Capital Gains Tax treatment when you sell, the fund has to have been a reporting fund for the whole time you held it. If your fund isn't on the list, or was only on it for part of the time you've held it, get advice. Some or all of the gain can be taxed as income.
Finding the figure in the fund's report
Every reporting fund has to publish a report for UK investors within 6 months of the end of each reporting period. It gives the ERI per share, the fund distribution date and whether the fund is still a reporting fund. The fund can send it to you, publish it on a website or print it in a UK newspaper. Start with the fund manager's website.
Here's what that looks like for one real fund: the accumulating shares of Vanguard FTSE All-World UCITS ETF (ticker VWRP). I've used it only to show how to read a report. This isn't a suggestion to buy, sell or hold it.
VWRP is a share class of Vanguard Funds plc. Vanguard's UK "Tax reporting" page lists one excess reportable income report a year for Vanguard Funds plc, each for a period ending on 30 June. This is the row for VWRP in the report for the period ending 30 June 2025:
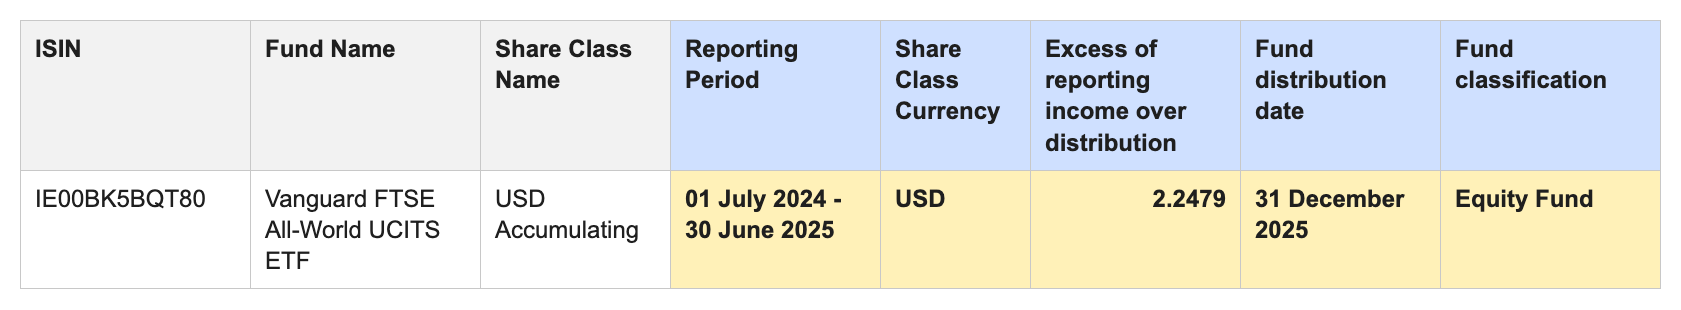
The highlighted columns are the ones you need:
- Reporting period: 1 July 2024 to 30 June 2025. If you held VWRP shares at the end of 30 June 2025, this row applies to you.
- Share class currency: USD. The ERI is in US dollars per share, so you'll convert it to pounds at the rate for 31 December 2025, the fund distribution date.
- Excess of reporting income over distribution: 2.2479. That's $2.2479 per share, so 100 shares would have $224.79 of ERI.
- Fund distribution date: 31 December 2025. The ERI goes on your 2025–26 tax return.
- Fund classification: Equity Fund. The ERI is taxed as a dividend. A fund marked as a bond fund has its ERI taxed as interest instead.
The distributing share class of the same fund shows 0 in the excess column for that period, because its payouts covered all its reported income. Those payouts are taxed as dividend income in the tax year they're paid.
Working out your ERI
Multiply the ERI per share by the number of shares you held at the end of the reporting period. If the figure is in another currency, convert it to pounds using the exchange rate for the fund distribution date. HMRC's notes for the foreign pages say to use the exchange rate at the time the income arose, and ERI counts as received on the fund distribution date.
HMRC publishes a spot rate for 31 December and 31 March each year. Those are the fund distribution dates for reporting periods ending on 30 June and 30 September. For other dates, HMRC publishes no daily rate and doesn't say which rate to use for ERI. Its savings and investment manual accepts a rate from a reputable source, such as your bank's rate for the day, used on the same basis every time. That guidance is written for savings and investments generally, not ERI, but it's the closest HMRC gets.
Say you hold 400 shares in a global index ETF, an accumulating equity fund priced in dollars. Its reporting period ends on 30 June 2026, and its report shows ERI of $1.8500 per share.
ERI on 400 shares, reporting period ending 30 June 2026
- 400 shares × $1.8500
- $740.00
- Converted at an assumed $1.25 to £1 on 31 December 2026
- £592
- Tax year it counts in
- 2026–27
- ERI to report
- £592
For an equity fund, that £592 is dividend income. Dividends have a £500 tax-free allowance. Above it, the 2026–27 rates are 10.75% for basic rate taxpayers, 35.75% for higher rate and 39.35% for additional rate. If your other dividends already use the allowance, the £592 costs a basic rate taxpayer £63.64 and a higher rate taxpayer £211.64. HMRC's notes say to include all dividend income on your return, even if it's under £500.
Equalisation can reduce this in the period you first buy into a fund. Part of what you paid for your shares was income the fund had already built up before you bought. Funds that run full equalisation give that amount per share in their report, and it can come off your ERI for those shares. If the report shows an equalisation figure and you bought during that period, HMRC's manual at IFM13328 shows how it's applied.
Where it goes on your tax return
ERI goes on the foreign pages of the Self Assessment return (form SA106), not the main return. For a fund taxed as a dividend, use the "Dividends from foreign companies" section. On the form for the 2025–26 tax year, that's one row per country:
Country code
The 3-letter code for the country the fund is based in, such as IRL for Ireland.
Income before foreign tax
Your ERI in pounds.
Foreign tax taken off
Any foreign tax on the income, in pounds.
Income after foreign tax
Column B minus column C. If column C is empty, it's the same as column B.
Total
The total of column F for all your foreign dividends.
For a bond fund, the ERI is interest, so it goes under "Interest and other income from overseas savings" on the same pages. It's taxed like other savings interest, and GOV.UK explains the tax-free amounts for savings. Box numbers can change from year to year, so check HMRC's notes for the foreign pages for the year you're filing.
A fund's report can come out late. If it arrives after you've filed, HMRC's manual expects you to amend your return.
ERI and Capital Gains Tax when you sell
You pay Income Tax on ERI you never got in cash, so HMRC adds it to what the shares cost you. When you sell, that makes your gain smaller. Without this, the same money would be taxed twice, once as income and again as part of the gain.
The ERI counts as extra cost on the fund distribution date. If you hold the shares in a section 104 pool, it goes into the pool's total cost on that date. If you sell only part of your holding, only the matching share of that cost comes off the gain, like any other cost in the pool. If you sell after the reporting period ends but before the fund distribution date, the ERI still counts as cost. For Capital Gains Tax, HMRC treats it as received just before your sale. For Income Tax, it still counts on the fund distribution date.
Say those 400 shares cost you £20,000 in total. Later in 2026–27, after 31 December 2026, you sell all 400 for £26,000. You pay higher rate Income Tax and have no other gains that year.
Selling 400 shares for £26,000 in 2026–27
- Gain without the ERI: £26,000 − £20,000
- £6,000
- Gain with the ERI: £26,000 − (£20,000 + £592)
- £5,408
- Tax without the ERI: £3,000 above the £3,000 CGT allowance at 24%
- £720
- Tax with the ERI: £2,408 above the allowance at 24%
- £577.92
- Capital Gains Tax saved by adding the ERI
- £142.08
Keep a record of the ERI you report each year for each fund, with the fund distribution date. You'll need the total when you sell, which may be years later. Our calculator doesn't include ERI yet, so the gain it shows for a reporting fund is before the ERI is added. If you sell your whole holding, take your total ERI off the gain it shows. For a part sale, work out the pool cost with the ERI included.
Distributing and accumulating classes: what changes on your return
For an equity fund, both classes' income goes in the same place on your return, the "Dividends from foreign companies" section of the foreign pages. Neither is taxed less, because the same income is taxed either way. What differs is where the figures come from and when the income is taxed:
| Distributing class | Accumulating class | |
|---|---|---|
| How the income is taxed | As dividends, in the tax year they're paid | As ERI, in the tax year of the fund distribution date |
| Where the figure comes from | Your broker's income statement | The fund's yearly report, per share, in the share class's currency, such as dollars |
| Working it out | Add up the dividends paid in the tax year, converted to pounds at the rate for each payment date if they aren't in pounds | ERI per share × shares held at the end of the reporting period, converted to pounds |
| ERI from the fund's report | Can be zero or very small, but check the report each year you hold shares at the end of the reporting period | All of the share class's reported income, each year you hold shares at the end of the reporting period |
| When you sell | Your cost is what you paid, plus any ERI | Your cost is what you paid, plus each year's ERI |
| Cash | Payouts arrive as cash, which you can spend or reinvest, and reinvesting can cost a dealing fee | No cash arrives, so the tax on the ERI is paid from other money |
If you hold a distributing class, most of your figures come from your broker's income statement. If you hold an accumulating class, you'll need the fund's report each year.
When to get help
Most people with a few reporting funds in an ordinary account can handle ERI themselves once they've found the reports. Some cases need a regulated tax adviser. One is a fund that isn't a reporting fund, or wasn't for part of the time you held it, because the gain may be taxed as income. Another is a fund whose classification changes between equity and bond from year to year. Another is equalisation across many purchases. The last is not being UK resident, or claiming relief under the foreign income and gains regime.
Work out your own CGT
Paste your trades from your broker and see your gain, allowance and tax in seconds.
Open the calculator →Sources on GOV.UK: HS265 Offshore funds, Approved offshore reporting funds, Self Assessment: Foreign (SA106). Last checked 26 September 2026.
This is an estimate, not financial or tax advice. It may contain mistakes and does not cover every situation, so check your figures with HMRC or a qualified adviser before you rely on them.